Scottish housing market facing ‘material’ pressures but affordability remains strong - Rettie research

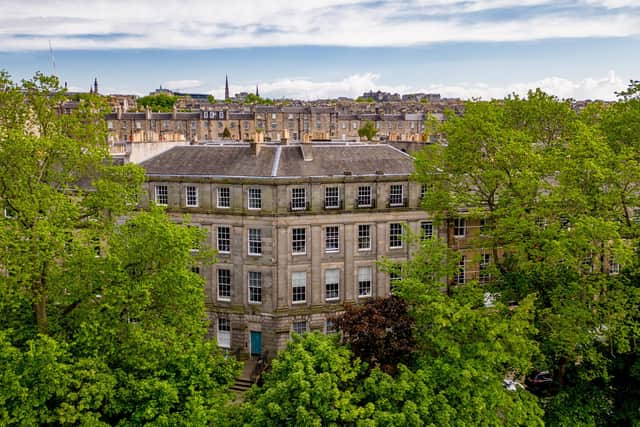
“The mortgage market is now out of its period of cautious recovery that had brought down mortgage rates and costs” – John Boyle, Rettie
Scotland’s housing market is facing “material” pressures amid rising interest rates but affordability remains strong, new research suggests.
The average monthly mortgage payment in Scotland now stands at about £1,200, compared to under £1,100 at the end of 2025, according to the latest study from Rettie, the upmarket estate agency and property consultancy headquartered in Edinburgh. It points to concerns about future interest rate increases having a dampening effect on both the mortgage and residential housing markets.
Despite this, housing demand remains “relatively resilient”, the firm noted, with overall Scottish sales in the year to September similar to last year, although sales were down 6 per cent in the third quarter compared to the preceding three-month period.
The report comes after the Bank of England’s monetary policy committee last week voted to hike the bank base rate from 3.75 per cent to 4 per cent, marking the first increase for more than three years. The central bank has warned that it may need to raise them further if inflationary pressures persist.
The vast majority of mortgage customers - almost 90 per cent - have fixed-rate deals and their monthly payments are not immediately affected by a rate change, However, their future deals are.
As of November 4, the average two-year fixed residential mortgage rate stood at 5.96 per cent, while the average five-year rate topped almost 6 per cent, according to financial information service Moneyfacts.
John Boyle, director of strategy and research at Rettie, said: “The mortgage market is now out of its period of cautious recovery that had brought down mortgage rates and costs. There has been a reversal in 2026 as a direct result of the Middle East conflict, which is beginning to have a material impact on housing and mortgage markets.
“Conditions do not look like improving soon and will likely become more challenging over the next six to 12 months,” he added. “The market has coped with steeper rises in mortgage rates and costs before and, and although the outlook looks bleaker than at the time of our previous report this time last year, the upside is that the housing market does remain active.”
Meanwhile, the average mortgage payment remains below the average private rent in Scotland by around 4 per cent and Scottish house sales have held up “reasonably well” through the third quarter, according to the Rettie research.
In the UK as a whole, the number of mortgage approvals were down by 19 per cent year-on-year to the end of September. First-time buyers make up more than half of mortgage sales in Scotland and the wider UK, which Rettie describes as the “lifeblood of the market”. And, in spite of government stimulus packages being in place to encourage buyers, the firm says government support will only slow any downturn.
Since the start of the latest Middle East conflict, mortgage rates have jumped from their three-year low, while the average two-year 85 per cent loan to value (LTV) rate has increased from 4.4 per cent to 5.1 per cent over the last two quarters of 2026.
Rettie has also found that affordability pressure, which can be measured by estimating the percentage of the average gross household income spent on the mortgage payment for the average house, is on the up.
Edinburgh has historically been the least affordable city in Scotland on this measure. After falling back for a time, the average mortgage payment in Scotland’s capital is back up to 38 per cent of the average household income in Q3.
Glasgow, meanwhile, remains at a significant discount to Edinburgh, with the average mortgage payment accounting for 27 per cent of average household income, in line with the national average but now also on a rising trend. However, affordability remains stronger in Scotland on average than it is in the wider UK.
The study comes after Scottish mortgage and property experts warned last week that a hike in interest rates would hit the affordability of first-time buyers and people already facing “significant financial pressures” as they seek to move home. They also called for Scotland’s Land and Buildings Transaction Tax (LBTT) to be reviewed in light of the increase in lending costs.
The rate increase to 4 per cent has sparked concerns about the impact on households already wrestling with the ongoing cost-of-living crisis.
Alan Cumming, head of sales and financial services at Rettie, said: “The findings in this briefing provide a clear reminder of the affordability pressures facing borrowers. Against that challenging backdrop, it is worth recognising that property prices across many parts of Scotland remain comparatively affordable against much of the rest of the UK. And it’s also important to remember that the housing market has continued to thrive through previous periods when interest rates were higher.
He added: “Government support can help first-time buyers take their first step onto the property ladder, while home movers may have greater flexibility than the headline figures suggest - where selling prices soften, this can often be balanced by securing better value on their onward purchase, reducing the overall impact across the move.
“For homeowners whose current fixed-rate mortgage deal is due to end within the next 12 months, the message is clear, namely seek advice early. Working with a mortgage broker who provides access to a wide range of products can help borrowers understand their options and secure the most competitive rate available in the circumstances.”
Comments
Want to join the conversation? Please or to comment on this article.