
Scotland’s spinouts are falling behind on funding
There’s a £2bn gap hiding in plain sight, writes Andrew Noble. Long-term capital from patient investors is what’s needed
Headlines over the summer suggested the tide of investment equity across the UK was shifting. After 15 years in the Golden Triangle’s shadow – where Oxford, Cambridge and London startups benefit from capital flows three times deeper than elsewhere – British Business Bank data showed other regions finally catching up. Scotland, in particular, saw its share rise 74 per cent year-on-year, beaten only by the North West at 82 per cent.
Yet look beyond the headlines and a different story emerges. Equity deals in spinouts UK-wide dropped by a third in the same period, and the same BBB report shows investment value falling 51 per cent nationally. Equity may be returning, but it isn’t flowing equitably.
At the heart of this mismatch is not just how much capital is being deployed, but the type of capital and the investors behind it. Much of Scotland’s uplift was driven by deals like Fidra Energy’s £445m round – the kind of fast-moving, commercially proven business that’s an easy, recognisable bet for most investors.
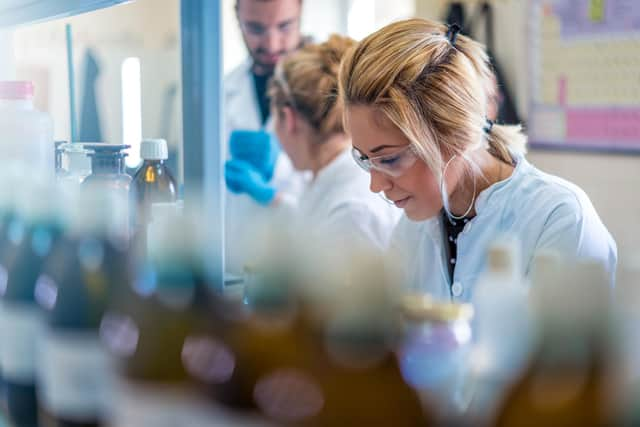

Spinouts don’t usually fit that mould. Many start with lab-proven technology that’s still untested at scale. The road is often expensive and unglamorous; seeking constant regulatory sign-offs, running trials to validate (or set back) years of work, and finding partners and customers willing to take a bet. Each step can take months before a penny of revenue is recorded, and none of it looks like traction to an investor trained to read growth curves.
Spinouts don’t just need capital, they need long-term capital from patient investors. That’s a very different discipline to backing an everyday startup, and in Scotland and the north especially, a lack of that discipline is creating a gap: for every £1bn of research generated in the South East, university-linked venture capital reaches roughly £937m. In the north that equivalent is just £175m. Sustained over a decade or more of underinvestment, this has created a shortfall in the region of £2bn and counting.
Scotland has more reason than most to feel this gap acutely. Its spinout deal count held up nearly three times more strongly than the national trend (down 12 per cent vs 33 per cent). Its investment value proved six times more resilient (8 per cent vs 51 per cent), overtaking London on spinout deals completed, 45 vs 28.
Scotland has 7.8 per cent of the UK population, yet houses 10 per cent of the UK’s university base, produces 13 per cent of the patent filings and wins 15.6 per cent of the research funding underpinning deeptech – twice the research funding per capita. Four of the UK's top 20 universities for spinout value creation are in Scotland and 85 per cent of research submitted by Scotland’s universities is rated world-leading or internationally excellent.
The wider market is waking up to what this kind of strength is worth. Spinouts claimed a record 12 per cent share of European VC last year, even as the wider market contracted. There's a question of sovereignty too. Ministers were reported to be exploring an exit tax to keep the value and IP of spinouts on British soil. The business department has since ruled that out, though the fact it was considered at all suggests a growing recognition of what's at stake.
None of this is to take away from the progress shown in the BBB report. It’s encouraging that founders across the UK are given greater access to the support needed to build and scale from home. We also don’t need to reinvent the wheel to push progress further.
BBB’s own reports show the capital is already moving and London’s dominance is loosening in a way it hasn’t for a decade. There's growing appetite for deeptech investments in the wake of life science and AI advances. Glasgow and Edinburgh have spent years positioning themselves as leaders in exactly the kind of IP-rich reindustrialisation that the UK’s spinout success is built on and Glasgow Tech Week was dominated by conversations on advanced manufacturing, suggesting a city on the rise in this space. What’s missing isn’[t infrastructure, it’s impetus.
If we can point as much capital towards solving the harder and slower problems as that going towards the easier wins, this year’s gains in resilience won’t just be proof the appetite exists, it’ll be the floor from whichScotland, the north and the whole UK builds the next decade..
Andrew Noble, General Partner at PXN Ventures
Comments
Want to join the conversation? Please or to comment on this article.